Dimitra DeFotis
Senior EditorMicron Earnings Preview: Triple-Digit EPS, Revenue Growth, and Strong Margins?
Dimitra DeFotis
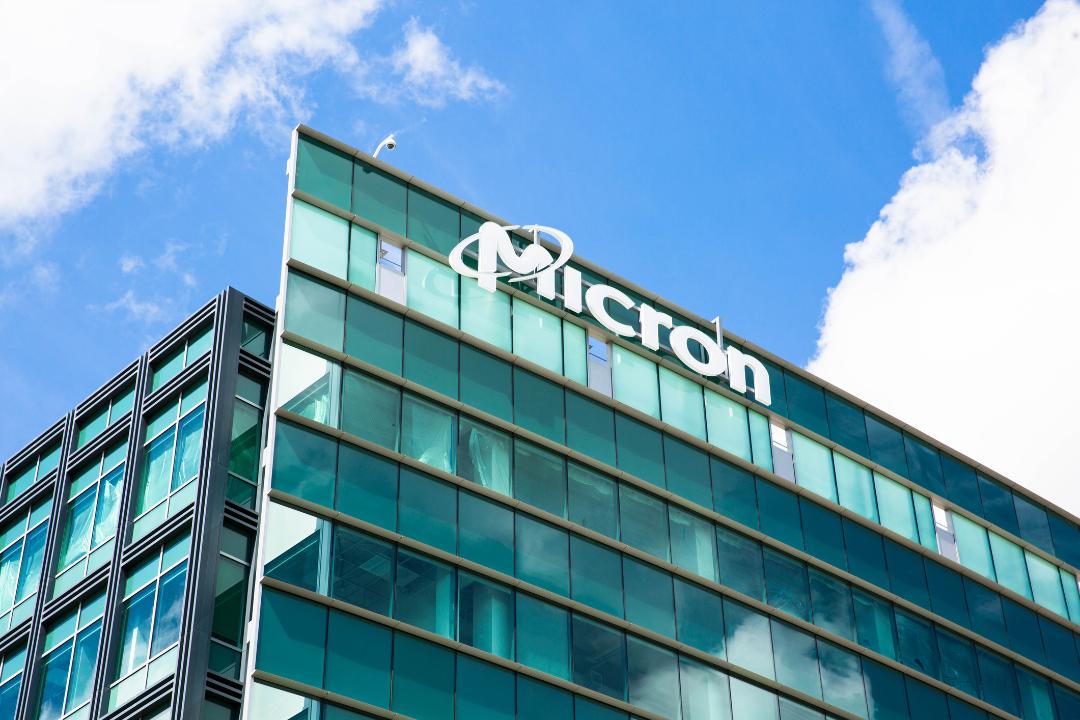
Senior EditorMemory and storage giant Micron Technology (MU) is expected to report triple-digit growth in earnings per share and revenue for the fiscal fourth quarter after today’s closing bell.
Expectations are high for the report: a 943% increase in fiscal fourth quarter earnings, to $31.61 per share, and a 350% increase in revenue, to $51B, according to Zacks.
Micron shares “have even higher options volume when you factor in the high stock price than names like Nvidia (NVDA) and Tesla (TSLA) lately,” notes Mike Khouw, chief strategist at YieldMax ETFs, in conversation with Nicole Petallides in a Schwab Network interview Tuesday. The options market shows a significant potential move in Micron shares of $80 +/- into the end of the week. At Tuesday’s close near $1,065, the stock was up 273% year to date, but is still trading at roughly 7x forward earnings, a discount to its historical P/E of about 10x. The PHLX Semiconductor Sector Index (SOX) was up 78% year to date. See: Why Micron Could Keep Surging After Its Massive Revenue Run.
The question is if margins above 80% are sustainable in the face of competition, especially from potential China newcomers, and any softening of demand in key end markets. Micron designs and manufactures memory and storage products including DRAM, NAND flash, NOR flash, SSDs, and high‑bandwidth memory (HBM) that is used in smartphones, PCs, data centers, automotive systems, and AI hardware.
For now, the margin outlook reflects tight supply and strong demand for DRAM and NAND storage chips, for Micron, SanDisk (SNDK), and peers. Much of this is due to the estimated $14T in cumulative data center capital spending through 2030; this spending leaves reason to believe that Micron can beat expectations for revenue, earnings, and produce 86% expected gross margin, says Daniel Newman, CEO of Futurum, the tech research firm.
He told Sam Vadas in a Schwab Network interview Tuesday that Micron has “all the control, the agreements, the pricing floors, and we cannot build out data center infrastructure without a ton of memory.” See: Daniel Newman on Anthropic's Value, AI Safety & MU Earnings Expectations.
What are the caveats for memory-sector players like Micron? Memory stocks have pulled back from recent record highs despite more strategic-customer and long-term agreements, "suggesting investors are more concerned about the memory cycle peaking, potentially as incremental capacity arrives in 2H27E,” Bank of America analysts said in a recent note. The consensus expects memory revenue growth to trail compute peers in 2027 and 2028, they note.
Micron’s performance year to date has significantly outpaced the semiconductor index, but will markets continue to reward triple-digit EPS and revenue growth prospects?
For this week's economic and earnings calendars, see Week Ahead: Watch Jobs Data, GDP, and Micron Technology (MU) Earnings
Featured Clips
AI Demand Powers SNDK Rally, Memory Cyclicality Poses Key Risk
► Play videoMeghan Welch on Defense, Aerospace M&A Impacts to Future Battlefields
Market Matters with Marley Kayden
► Play video